Good morning, Slaters!Every rate decision has a setting. Today's setting is ugly. The 10-year Treasury yield touched 5.04% yesterday, its highest since 2007. Brent crude is trading above $105 after Saudi Arabia's East-West pipeline went offline. Diesel just crossed $6 a gallon for the first time in American history. And the consumer, the last pillar holding up the spending economy, showed up to July with a 0.6% decline in retail sales. That is the room Kevin Warsh walks into at 2 p.m. ET today. CME FedWatch puts the odds of a 25-basis-point hike at 93%. If it happens, it will be the first rate increase since July 2023, lifting the target range to 3.75% to 4.00%. The dot plot arrives with it. The question is not whether the Fed hikes. The question is what Warsh says about what comes next, because the bond market is already writing its own monetary policy from the long end. Let's frame the day. 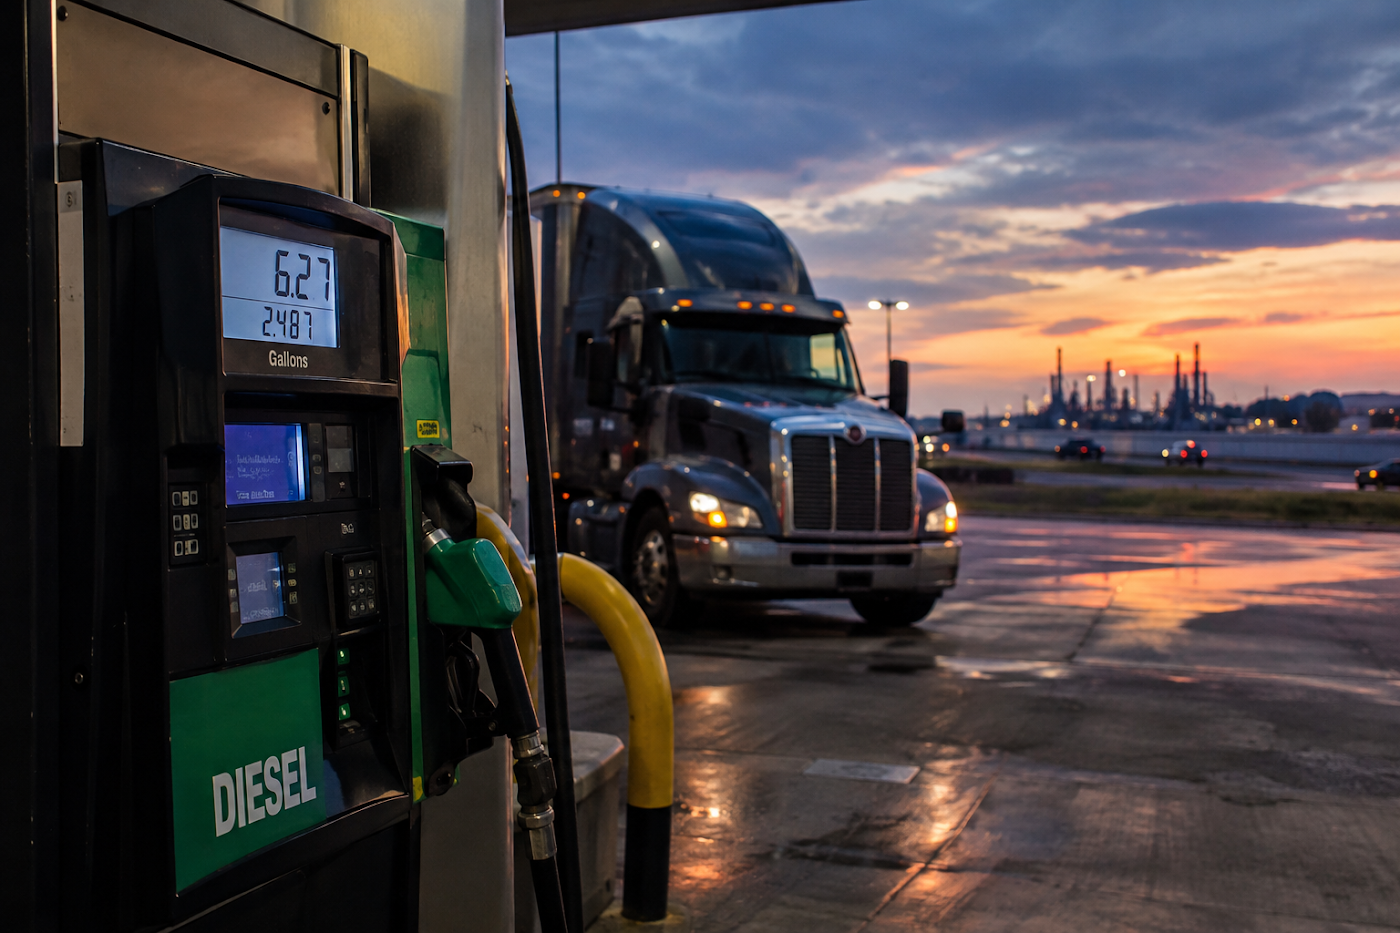
Daybreak The most loaded session of 2026 starts in hoursTwo data events arrive today within the same session, and the sequencing matters. At 8:30 a.m. ET, the Census Bureau releases August retail sales. July showed a 0.6% monthly decline to $763.6 billion. NRSInsights data already showed independent retailers posting a 1.1% same-store sales decline for August. If the Census confirms that direction, traders have five and a half hours to reprice risk before the Fed speaks. At 2 p.m. ET, the FOMC announces. The 93% probability of a 25-basis-point hike means the move is priced. What is not priced is the dot plot and Warsh's press conference at 2:30. Three dissents in July. Jackson Hole flipped pricing from 70% hold to 56% hike in one afternoon. Barclays expects two hikes this year, September and December. If the dots confirm that path, the short end reprices immediately. The market signal? The retail number is the appetiser. The dot plot is the meal. If Warsh signals December is live, the 2-year yield moves before 3 p.m. and rate-sensitive equities (homebuilders, REITs, small caps) will feel it before the bell. PREMIER FEATURE There's a website called RentAHuman.ai. Its tagline: "Robots need your body." 721,000 people across 100 countries have signed up. And according to Alexander Green - the man who bought Apple under $1, Netflix at $1.62, Amazon under $2* - this is the clearest signal yet that Phase 2 of the AI supercycle has arrived. (Split adjusted prices) He's identified three companies set to dominate this next phase. CLICK HERE TO WATCH THE FULL STORY FOR FREE Pulse Check The 10-year just rewrote the rulebookTuesday's market told a straightforward story. The S&P 500 (SPX) fell 0.45% to 7,585. The Nasdaq Composite dropped 0.78% to 25,981. The Dow Jones Industrial Average lost 328 points, or 0.63%, to close at 52,093. Both the S&P and Nasdaq declined for a second consecutive session. The real story was in bonds. The 10-year Treasury yield surged to 5.04% intraday, its highest since 2007, before settling near 5.00%. That is not a rate-hike trade. That is the bond market repricing fiscal risk and term premium in real time. Oil added pressure. Brent crude rose to $107.50 after Saudi Arabia's East-West pipeline remained offline. Goldman Sachs warned a prolonged shutdown could push Brent above $120. Some AI names bounced: Advanced Micro Devices (AMD) gained 2%, Qualcomm (QCOM) rose 4%. But the broader tone was defensive. The market signal? With the 10-year above 5%, every forward P/E multiple in the S&P 500 is competing against a risk-free return that did not exist two months ago. Until yields stabilise, equity rallies get sold. Who Moved the Mic? Moynihan just told Wall Street the advisory boom is over (for now)Bank of America (BAC) CEO Brian Moynihan stood up at the Barclays Global Financial Services Conference on Monday and gave the kind of guidance that makes trading desks wince. Third-quarter investment banking fees: $1.6 billion to $1.8 billion. Wall Street consensus: $2 billion. That is a decline of more than 10% year-over-year, coming off a Q2 that featured a 50% jump in advisory fees and a 33% surge in trading revenue. Sales and trading revenue? Roughly flat, after a blockbuster first half. BAC shares fell 5% on the day. Goldman Sachs (GS), Citigroup (C), and Wells Fargo (WFC) all dropped in sympathy. The S&P 500 banking index slid 2.7%. Moynihan tried to soften it. NII growth is at the upper end of 6% to 8% guidance. Wealth management fees up 10% to 15%. "The underlying economy is good and the business is good," he said. "It's kind of this capital markets movement makes you not feel good, but it's actually a pretty good quarter." When the CEO of the second-largest bank in America spends half his conference appearance explaining why a dealmaking slowdown does not mean the whole bank is slowing, the market hears the first half louder. The market signal? Watch the other big banks closely. Citigroup CFO Gonzalo Luchetti guided to low-single-digit revenue growth in Q3 advisory, saying "September is a key month." If the September pipeline does not materialise, the Wall Street revenue supercycle narrative that powered bank stocks through the first half gets a serious revision. FROM OUR SPONSORS You’re Being LIED To About The Iran War
Forget EVERYTHING you’ve heard about the Iran war. Especially the reasons why we’re bombing the country. Because THIS is the real reason. World, Uncomplicated Saudi Arabia's backup plan just went offlineThe East-West pipeline was supposed to be the insurance policy. When the Strait of Hormuz became functionally closed earlier this year, Saudi Arabia's 745-mile pipeline offered an alternative: crude could bypass the strait entirely, flowing from Persian Gulf fields to the Red Sea port of Yanbu. It carried up to 5 million barrels per day. It was the world's largest workaround for the most important chokepoint in global energy. Last Thursday, Houthi drones hit the pipeline. Saudi officials told the AP it could take three to five weeks to repair. On Monday, Brent crude jumped nearly 5% to $109.44. By Tuesday, it settled near $107.50, with Goldman Sachs warning of a move to $120 if the shutdown persists. The chain reaction is mechanical. Hormuz contested. Pipeline offline. Saudi Aramco cancelling September cargoes to Europe. Vessel traffic through the strait fell to four ships Monday from ten the day before. Libya suspended two oilfield operations. Half of Russia's top diesel refineries have cut output from Ukrainian drone strikes. The market signal? Every link in the global energy supply chain is under simultaneous stress. U.S. diesel crossed $6 per gallon for the first time in history last week. Gas hit $4.32, a new September record. These costs feed directly into CPI, freight costs, and the inflation expectations the Fed is trying to manage with the rate decision it announces in hours. Energy is no longer a separate trade. It is the inflation trade. Beyond the Candles SpaceX is now a $143 stock with a $225 memoryThree months after the largest IPO in history, SpaceX (SPCX) is telling a story the prospectus did not prepare investors for. The stock listed at $135 on June 12. It opened at $161 and briefly touched a market cap near $3 trillion in the euphoria that followed. By late July it had crashed below its IPO price, trading as low as $104.83. A strong Q2 earnings beat ($7.81 billion in revenue, above the $6.93 billion consensus) pulled it back above $135 in August. As of Tuesday's close, SPCX sat at $148, well below the June peak but above its IPO price. The 52-week range tells the whole story: $104.83 to $225.64. Then Musk made it weirder. He left the door open to a Tesla-SpaceX merger last week, a comment that sent both stocks lower as investors tried to figure out what a combined entity would even look like under dual-class voting control. The structural issue is simpler than the headlines. SPCX has had three major lockup expirations since June, each releasing hundreds of millions of insider shares into the float. The third, on September 9, unlocked roughly 319 million shares. Every lockup creates selling pressure that the stock must absorb through organic demand. So far it has. Barely. Analysts remain bullish on paper. The average 12-month target is $222. Citi reiterated Buy with a $200 target after Q2 earnings. But the gap between where SPCX trades and where analysts say it belongs is one of the widest in the Nasdaq 100. The market signal? SPCX is a proxy for two things at once: the space economy and Musk's conglomerate ambitions. If Q3 earnings (due in November) show Starlink subscriber growth accelerating, the stock has room to close the gap to targets. If the Tesla merger talk gets louder, the discount widens, because conglomerate risk never trades at a premium. Under the Hood $6 diesel is a tax on everything you buyHere is a number that does not get enough airtime: $34.8 billion. That is how much the diesel price surge has added in direct fuel costs for commercial transport since the U.S.-Iran conflict began in late February, according to the American Action Forum. The diesel crack spread, a measure of refiner margins, surged past $100 per barrel on September 1, a fivefold jump from the pre-conflict baseline of roughly $20. Diesel is not gasoline. When gasoline gets expensive, people drive less. When diesel gets expensive, everything gets expensive. Every Amazon package, every gallon of milk, every piece of lumber moves on diesel. Refineries are at 98% capacity. Inventories sit 13% below their five-year average. The two largest external threats to diesel supply, Hormuz and Ukrainian strikes on Russian refineries, are both intensifying at once. GasBuddy analyst Patrick De Haan put it bluntly: record diesel will "reignite inflation up and down the supply chain." The Fed is raising rates today into an economy where the inflationary force is not excess demand. It is a supply shock delivered by a pipeline, a strait, and a war. The market signal? Watch freight and logistics stocks. If diesel holds above $6 through October, margin compression in consumer goods, retail, and food distribution becomes unavoidable. The companies that own their own fleets or have locked in fuel hedges will outperform. The ones that did not just got a new line item they cannot control. What's Brewing - The retail number hits at 8:30 a.m. ET. If August confirms July's downtrend, watch the SPDR S&P Retail ETF, which closed Tuesday at $85.52, already down 2.4% on the session. The consumer-resilience thesis gets its most direct test of the quarter.
- The Anthropic IPO timeline is the most consequential corporate calendar item in AI. Backers are targeting an October listing at up to $2 trillion. Revenue run rate exceeded $65 billion by July. If Anthropic moves forward while OpenAI delays, the competitive positioning of the two largest AI labs diverges for the first time.
- Brent crude's next level matters more than any analyst target. Goldman flagged $120 if the Saudi pipeline stays offline. Aramco has given no repair timeline. If Brent closes above $110 this week, every Q4 inflation forecast needs rewriting.
- The market signal across all three? Retail data tests the consumer. The Fed tests the rate path. Oil tests the inflation forecast. All three land in the same 24-hour window. That is not a coincidence. That is the market's stress test for the second half of 2026.
Meme of the Day 
That's it for today's Slate. The most consequential session of 2026 starts in hours. Retail at 8:30. Decision at 2. Press conference at 2:30. Stay very close to the feed. Today's reply prompt: If you could ask Warsh one question at the press conference, what would it be? FREE FINANCIALMARKETS.COM ALERTS The Next Market Move Could Start With One Alert Get breaking market developments, trade ideas, analyst signals and upcoming catalysts sent directly to your phone. Markets move quickly. Now your information can too. START GETTING FREE ALERTS → |