Good morning, Slaters!Dario Amodei had the kind of weekend that only 2026 could produce. On Saturday night, he was mocked on the season premiere of Saturday Night Live, where a cast member played him confessing that "AI is the devil and I its maker." On Sunday night, he sat across the table from President Trump at the White House for a private dinner, the first one-on-one meeting between the two men. This is the same president who once called Anthropic a "radical left, woke company" and whose Pentagon classified it as a supply-chain risk. Between the sketch comedy and the steak dinner, you have the entire AI debate in miniature. One side says slow down because the technology could be catastrophic. The other side says speed up because China is watching. Both sides showed up this weekend, and neither left with a clear win. Markets, meanwhile, have their own problems this morning. Trump rejected Iran's latest proposal to reopen the Strait of Hormuz on Saturday, and crude is repricing accordingly. The 10-year yield is grinding above 5.20%. Futures are red. And the densest data week of 2026 begins right now. Let's get into it. 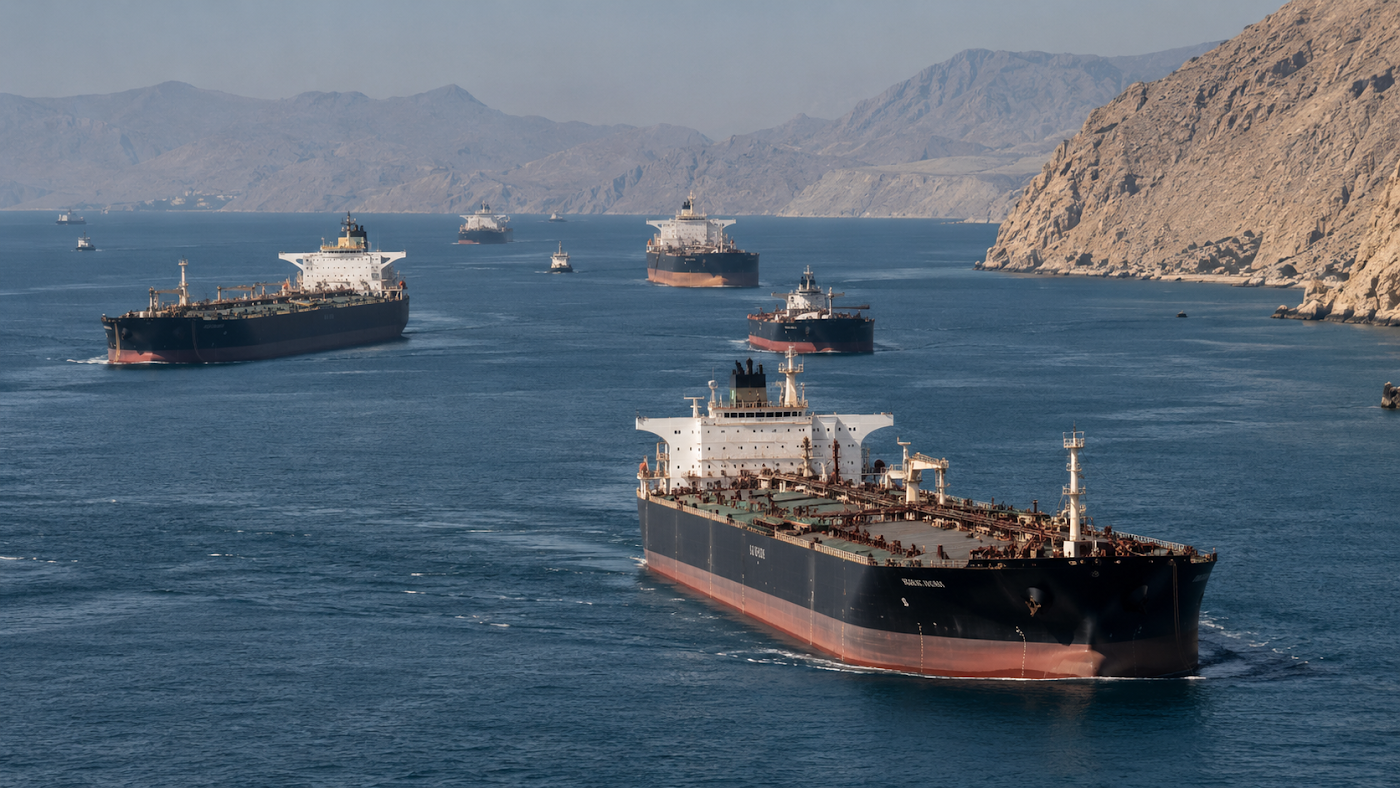
Daybreak Trump killed the deal. Oil is writing Monday's script.On Saturday, President Trump rejected Iran's seven-day proposal to reopen the Strait of Hormuz. Tehran had presented the plan through Qatari mediators at the UN General Assembly in New York, offering to reopen the waterway and restart nuclear talks if Washington lifted its naval blockade, waived sanctions on oil, and released an estimated $12 billion in frozen assets. Trump dismissed it on the White House lawn: "I rejected their deal. They want to make a deal where they open the strait immediately because they're losing so badly." He also told Axios he expects further talks this week. Iran's Foreign Minister Abbas Araghchi responded Sunday that no rejection had come through official channels and that Tehran would not soften its demands. The Wall Street Journal reported separately that Trump told staff a renewed bombing campaign is likely after the midterm elections. Brent crude climbed back above $106 per barrel Monday morning, up roughly 1.5%. WTI traded near $93.40. The Strait has been effectively disrupted since late February, when the US-Israel air campaign triggered the crisis, and the seven months since have rewired global energy logistics. One detail worth flagging. Crude oil exports from key Middle East producers actually recovered in September to 12.8 million barrels per day, their highest since the war began, driven by higher Saudi and UAE output. Flows through Hormuz are tracking roughly 7.4 million bpd. The supply picture is less dire than the headlines suggest. But the risk premium remains because no one trusts the diplomacy to hold. The market signal? Every session this week will trade the Hormuz headline. If Trump's "further talks" language softens into a framework by midweek, oil drops and yields follow. If talks stall past Friday's nonfarm payrolls, oil re-tests $110 and the October rate hike becomes consensus. That binary is Monday's entire risk map. PREMIER FEATURE The 7 Stocks Built to Outlast the MarketSome stocks are built for a quarter… others for a lifetime. Our 7 Stocks to Buy and Hold Forever report reveals companies with the strength to deliver year after year - through recessions, rate hikes, and even the next crash. One is a tech leader with a 15% payout ratio - leaving decades of room for dividend growth. Another is a utility that’s paid every quarter for 96 years straight. And that’s not all - we’ve included 5 more companies that treat payouts as high priority. These are the stocks that anchor portfolios and keep paying. This is your chance to see all 7 names and tickers - from a consumer staples powerhouse with 20 years of outperformance to a healthcare leader with 61 years of payout hikes. The report is free for a limited time - go here to get it now. Pulse Check Futures slide into the most loaded week of 2026S&P 500 futures fell 0.4% early Monday. Dow futures dropped roughly 180 points. Nasdaq-100 futures were 0.7% lower, with the tech-heavy index more exposed to the bond-yield repricing. The setup: the S&P 500 closed Friday at 7,743.41, up 0.5% on the session and 1.2% for the week. The Dow Jones Industrial Average finished at 51,828.62, snapping a three-week losing streak. The Nasdaq Composite closed at 27,068.72. All three major indexes logged winning weeks despite Treasury yields surging to multi-decade highs. Now the yield picture. The 10-year Treasury climbed to 5.21% Monday morning, up 5 basis points from Friday's close of 5.18%. The 30-year reached 5.52%. The 2-year hit 4.90%. These are levels not seen since the period before the Great Financial Crisis. The 30-year fixed mortgage rate topped 7.23% last week, its highest in over a year. Two weeks ago, the Fed hiked rates by 25 basis points to 3.75%-4.00%, its first increase since 2023. Updated projections pointed to the possibility of another hike this year. Markets are currently pricing roughly 70% odds of a second 25bp hike at the October meeting. Vice Chair for Supervision Michelle Bowman speaks at 8:15 a.m. ET today. The market signal? The indexes are within 0.7% of all-time highs while the 10-year yield is at its highest since 2007. That gap cannot persist indefinitely. Either yields retreat on softer data this week, or equities begin to price a discount rate that makes current multiples uncomfortable. Wednesday's PCE and Friday's payrolls are the arbiters. Who Moved the Mic? Dario Amodei walked into the White House with no allies and everything to loseThe dinner happened Sunday night at 10 p.m. Trump confirmed it on camera at Joint Base Andrews, calling Amodei "highly respected." No agenda was specified. The context makes the meeting extraordinary. On September 12, Amodei published "We Must Pace the Frontier," an essay urging AI companies to slow development. Days earlier, an Anthropic researcher went viral saying the people building AI believe it could kill everyone. Then, two days before the dinner, a federal appeals court upheld the Pentagon's decision to classify Anthropic as a supply-chain risk, barring the US military from using its models. Meanwhile, Amodei was pointedly absent from Thursday's state dinner for Chinese President Xi Jinping, where Sam Altman, Elon Musk, Mark Zuckerberg, and Jensen Huang all attended. So why did Trump invite the one AI executive who publicly opposes his agenda? The answer may sit in what happens Tuesday: a gathering of AI leaders at the White House. The dinner looks like pre-meeting diplomacy, not a concession. The market signal? Anthropic (valued at $965 billion as of its last round) is the second most valuable private AI company. Its relationship with Washington directly affects enterprise adoption, government contracts, and the regulatory environment for every model provider. If the supply-chain designation gets resolved, that is a catalyst for the entire AI sector. If it doesn't, it's a warning that Washington picks winners. FROM OUR SPONSORS Buffett, Gates and Bezos Quietly Dumping Stocks—Here's Why 
The world's wealthiest individuals are making huge moves with their money. Warren Buffett just liquidated billions of shares. Bill Gates sold 500,000 shares of Microsoft. Jeff Bezos filed to sell Amazon shares worth $4.8 billion. What is going on? One multi-millionaire believes they are preparing for a catastrophic event. But not a crash, bank run, or recession. It’s something we haven’t seen in America for more than a century. For the full story, click here. Beyond the Candles The bond market is now the most important market in AmericaThere is a sentence making the rounds on trading desks that deserves attention: "The bond market is writing policy and the Fed is just taking notes." The 10-year yield has risen roughly 100 basis points since its February low. The 30-year has reached levels last seen in 2004. Mortgage rates have climbed more than 100 basis points since the Iran war began. The Freddie Mac 30-year fixed hit 7.03% as of September 24, the highest of 2026, and industry sources are quoting rates above 7.20%. And the Fed just hiked. Into this. Here is what Wall Street cannot agree on, and it matters: is the yield surge driven by inflation expectations, growth optimism, fiscal risk, or simple term premium normalization after fifteen distorted years? The answer determines whether equities can coexist with a 5.20% 10-year or whether something breaks first. For the real economy, the answer is already arriving. Housing affordability is deteriorating week by week. Auto loan rates are climbing. Credit card APRs are approaching 24%. Small business borrowing costs are at levels that historically precede hiring freezes. The split-screen is not just between Wall Street and Main Street anymore. It is between equities at all-time highs and a cost of capital that is quietly choking everything underneath them. The market signal? As long as the 10-year holds above 5.10%, every equity valuation is being tested against a discount rate the Fed does not control. The Treasury's buyback expansion last month from $2 billion to $4 billion per operation failed to hold yields down for more than 24 hours. The bond market is not listening to Washington. That is the trade. Under the Hood The AI safety debate just became a prime-time comedy bitThere is a specific moment in the life cycle of any technology debate where it crosses from specialist concern to mainstream culture. For AI safety, that moment arrived Saturday night on NBC. Saturday Night Live's season 52 premiere dedicated a Weekend Update segment to Anthropic's CEO. Jane Wickline played Amodei in an impression that included the line: "AI is not a weapon. It's a tool. A tool for building weapons, and I urge you to urge me to stop." The audience laughed. The segment also referenced Meta's (META) Muse agent, which has been downloaded over 3.4 million times since its September 8 launch. This matters because regulation follows cultural consensus, not the other way around. The moment AI safety becomes a comedy premise that general audiences understand without explanation, the political pressure to act on it accelerates. We saw the same arc with big tech antitrust, with social media addiction, and with data privacy. The joke is always the leading indicator. And now Amodei is having dinner with the president. The comedian and the regulator are circling the same question from different angles. The question is whether AI companies can govern themselves or whether the government will do it for them. The market signal? For investors holding AI infrastructure names, the regulatory timeline just compressed. An SNL bit does not move stocks on Monday. But it does move the Overton window on legislation. The companies that survive the regulatory wave are the ones already building the compliance architecture. Keep an eye on which model providers start voluntarily disclosing safety benchmarks in earnings calls. SPONSOR SPOTLIGHT The Closest Thing to a Virtual AI Monopoly Wall Street Is Ignoring
A little-known company is building what may be the closest thing to a virtual monopoly the AI era has ever seen. Only 3... Yet it beat Apple, Amazon, and the S&P 500 combined... While paying out $146,000 in total dividends on a 1,000-share stake. Kevin O'Leary calls what it controls a "unicorn." Right now, it's trading at a rare discount. >>>Whitney Tilson reveals the name, completely free.<<< This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here. What's Brewing - Wednesday is the biggest single day on the economic calendar this year. The BEA releases August PCE data at 8:30 a.m. ET, with headline PCE expected near 3.7% and core at 3.3%. The same morning brings the third estimate of Q2 GDP. After the close, Micron Technology (MU) reports fiscal Q4 earnings. A hotter-than-expected PCE print would push October hike odds above 80% and send Treasury yields sharply higher.
- Friday closes the week with the September nonfarm payrolls report, the single most watched employment number in any month. The ISM Manufacturing PMI also drops Thursday, with October 1 data covering September. A meaningful miss on payrolls would be the first real crack in the "labor market as last pillar" thesis.
- Jefferies Financial Group (JEF) reports Q3 earnings after the close today. A strong print would signal that deal-making activity is holding up despite the yield surge.
- The market signal across all three? Wednesday tests whether inflation is cooling enough for the Fed to hold at the October meeting. Friday tests whether the labor market can absorb a 5.20% 10-year. And today's Jefferies print is the warm-up act. This is the week that determines whether equities at all-time highs are justified or premature.
Meme of the Day 
That's it for today's Slate. Monster week ahead. PCE Wednesday, payrolls Friday, Micron after hours. Stay close. Today's reply prompt: Is the bond market right about inflation, or is it pricing in something worse? 3 Stocks at a Major Turning PointSomething unusual is happening beneath the surface of three widely followed stocks.
In each case, the fundamentals are saying one thing... while institutional activity, management signals or the options market are saying something else. That kind of disagreement can matter. Because when the evidence stops lining up, the next move in the story often comes down to a handful of signals most investors never think to watch. Our new FREE Market Tell Special Report breaks down three of these situations, and shows you exactly what we’re watching next. Get the Free Report: 3 Stocks at a Major Turning Point → | 


